Documents, timelines and source material connected to the show. Read it yourself. Verify it independently. Make up your own mind.
01
CASE FILE 005 • SOURCE LOCK UPDATED SEPTEMBER 6, 2026
The Same Plumbing Keeps Showing Up: AMC, Alpaca, and the FTX-Adjacent Network
Robinhood's AMC product is Series 191, a tokenised debt security issued by Robinhood Assets Jersey. Its terms name Alpaca Securities as both custodian and broker, permit lending to a Prime Borrower and further lending to End Borrowers, and give the token holder no AMC ownership or voting rights.
Confirmed finding: The legal structure, lending authority and Alpaca relationship are documented. Alpaca also publishes five available execution partners. The public record does not identify which partner handled any Series 191 trade, hedge, loan or redemption.
DOCUMENTS BEFORE DIAGRAMSFive possible doors. No Series 191 door receipt.
CONFIRMED
RHJ issued Series 191, not AMC Entertainment.
Bitstamp Global is the authorised offeror.
Alpaca is the named custodian and broker.
Lending and further lending are contractually permitted.
GameStop Series 45 used the same core architecture first.
NOT YET PROVEN
Which firm executed or hedged the first AMC mint.
That any Series 191 AMC share was actually lent.
That the token caused an AMC price movement.
That a prohibited United States sale occurred.
That the product or any transaction was fraudulent.
CONTRADICTIONS AND TENSIONS
Robinhood says every token is backed one for one and monitored daily, but the public chain cannot display the private custody ledger.
Token holders get no AMC rights while the referenced AMC shares may be lent and replaced by other eligible collateral.
AMC did not issue or approve the product, although its name and price supply the reference exposure.
These are audit tensions, not proof that the backing claim is false or that a law was violated.
RECORDS NEEDED
Series 191 Alpaca custody and position statements.
Hedge confirmations for the August 13 first mint.
Customer-specific Rule 606 routing.
Prime and End Borrower securities-loan tickets.
Daily collateral quantities, substitutions, marks, liens and reuse restrictions.
ALPACA'S PUBLISHED PANEL
Available execution partners
Virtu Americas NITE
Citadel Securities CDRG
Jane Street Capital JNST
ION Group through DASH DASH
Global Trading Systems GTSM
This list establishes available routes. It does not establish the executor or venue for any AMC Series 191 order.
FTX-ADJACENT RECORD
Jane StreetBankman-Fried and Ellison worked there before FTX and Alameda.Reuters source ↗
Citadel SecuritiesBrett Harrison moved from a senior technology role there to become FTX US president.FTX US announcement ↗
Pyth networkFTX, Virtu and GTS appeared as publishers; Jane Street joined later in 2021.Pyth history ↗
ION and DASHION acquired DASH in 2021. No comparable direct FTX link has been verified.ION release ↗
Personnel history and shared infrastructure prove proximity, not coordination, misconduct or an AMC transaction.
02
APE VOTE AND CONVERSION REPORT • 50 MIN 10 SEC
APE's Magical Voting Act: Retail Did Nothing. The Vote Still Passed.
The completed report reconstructs AMC's March 2023 vote, the treatment of uninstructed common shares and APE units, the outcome determining proportional APE block, and the August reverse split and conversion records that still require an independent reconciliation.
Finding: Before proportional APE votes were included, Proposal 1 was 60,752,666 affirmative votes short and Proposal 2 was 66,690,406 short. Both passed after the Depositary applied the disclosed proportional voting rule. That proves the mechanism was outcome determining. It does not prove counterfeit APE, naked shorting, vanished units or fraud.
Total voting interests
1.447B
Proportional APE votes
346.55M
Proposal 1 shortfall
60.75M
Proposal 2 shortfall
66.69M
Records still needed: Transfer agent and Depositary control totals, DTC participant positions, vote tabulator work papers, broker deliverable records, conversion issuance totals, fractional share accounting and settlement distribution totals.
Watch the complete report with its original picture and audio. The arithmetic is public; the institutional bridge still needs independent, anonymized control totals.
03
RECENT SHOW EVIDENCE • AUGUST 31, 2026
AMC: Apparently, T Plus Zero Audited the Debt Vessel and Forgot to Open the Vault
Robinhood's governing documents, the canonical AMC token, the reported overnight price divergence and the missing bridge between the public token ledger and the private broker, settlement, custody and lending records.
Finding: The public chain can show token supply and movement. It does not independently prove that every corresponding AMC share was purchased, settled, allocated, continuously held and unencumbered. The price event does not by itself prove missing collateral, manipulation or fraud.
VISIBLE VESSEL. PRIVATE CARGO.One claim requires two reconciled ledgers.
Lock the canonical token contract and supply
Match each creation to the authorized participant
Produce the broker trade and settlement identifier
Reconcile settled AMC custody to token liability
Disclose every loan, lien and collateral substitution
Robinhood describes the product as debt issued by Robinhood Assets Jersey, not stock issued by AMC.
Token holders receive economic exposure without direct AMC shareholder rights.
One for one backing remains an issuer representation until the token and custody records are reconciled.
04
RECENT SHOW EVIDENCE • AUGUST 31, 2026
Apparently, the Coincidence Filed Regulatory Paperwork
The governing FTX and CM Equity product documents, reported hedge activity, Interactive Brokers routing records, Citadel execution reporting and AMC settlement failures are assembled into one testable operational pathway.
Finding: The public record documents the pathway and the categories of activity. It does not identify a specific CM Equity AMC order, beneficial owner, executing actor or failed delivery without the customer level records.
The brief collects FOIA emails concerning the Next Bridge subscription rights filing, broker operational concerns, shares on loan and future reconciliation after the MMTLP trading halt.
Record boundary: The emails document that the concerns were raised. Conclusions in the brief about motive, violations or a cover up are analysis and are not adjudicated findings established by the emails alone.
Ten independently rehashed venue files produced 19,560,345 normalized market by order records and 103 reconstructed AMC displayed bid chains. Across two separate episodes, a maximum of 863,079 displayed shares was removed with zero executions and zero replacement chains inside the frozen evidence set.
Finding: Two June 2 bid side episodes passed the frozen structural, repetition, synchronization, directional response and control day gates at the 250,000 dollar threshold. The public data do not identify the actor, beneficial owner, purpose, related trade or intent.
RECONSTRUCTED EPISODESTwo events. One date. Exact limits.
12:10:12 P.M. CDT
Seven venue withdrawal
Duration
0.807 sec
Chains
74
Shares
472,579
Notional
$31.39M
Five component bursts across seven venues. Frozen downward response measured 17.84 basis points at 100 milliseconds, 10.69 at one second and 23.60 at five seconds.
12:55:30 P.M. CDT
Three venue withdrawal
Duration
3.895 sec
Chains
29
Shares
390,500
Notional
$24.54M
Four component bursts across BATS, EDGX and Nasdaq. Frozen downward response measured 11.00 basis points at 100 milliseconds, 6.47 at one second and 6.46 at five seconds.
FIXED DOLLAR CONTROL$250K
AMC 2 strict leads • GME, BB, CNK and Ford 0
FIXED DOLLAR CONTROL$500K
AMC 1 strict lead • GME, BB, CNK and Ford 0
All 990 symbol, date and venue classifications reconciled.
The follow up audit resolved 99.404% of initially unmatched Fill shares. The 0.337% residual was excluded from candidate screening.
Both leads occurred on one date, so they are not two independent statistical observations. The empirical limits remain one of 19 AMC dates and one of five tested securities.
07
SHOW 2 • CASE FILE 003 • AUGUST 13, 2026
AMC APE and the Court Case: The 41 Day Settlement and the Missing Ledger
The public record fixes the path from the February 20 complaint to the April 2 binding term sheet, the settlement economics, the ACERS account history and the records capable of identifying any executing broker, stock loan borrower or outside influence.
Finding: The settlement was rapid and early stage, but it was judicially approved after revision and affirmed on appeal. The Court did not find fraud, conspiracy, collusion, Citadel involvement or BNY Mellon control. Those specific attribution questions remain unproved.
THE 41 DAY RECORDThe timeline is proved. Attribution is not.
ACERS and Franchi or Munoz actions filed
Cases consolidated and lead counsel appointed
AMC stockholder special meeting
Mediation began approximately two weeks later
Binding settlement term sheet executed
Unopposed motion sought to lift the status quo order
ACERS AND CIM ACCOUNT MATCH
Nearly identical AMC reductions
ACERS62.51599%
2,345 shares to 879
CIM62.52301%
20,642 shares to 7,736
The difference is approximately 0.00702 percentage points. This strongly supports a pro rata managed account allocation. It does not identify the parent order or executing broker.
ACERS sold 1,173 AMC shares on May 27, 2021 and 293 shares on June 2, then retained 879 and received 879 APE units on August 22, 2022.
The Court awarded counsel 12% of the settlement consideration and approved 5,000 dollar incentives for each named plaintiff from the fee award.
The decisive records are CIM order memoranda, BNY Mellon transaction and stock loan ledgers, proxy and corporate action subledgers, and the litigation communication files.
08
CASE FILE 002 • AUGUST 7, 2026
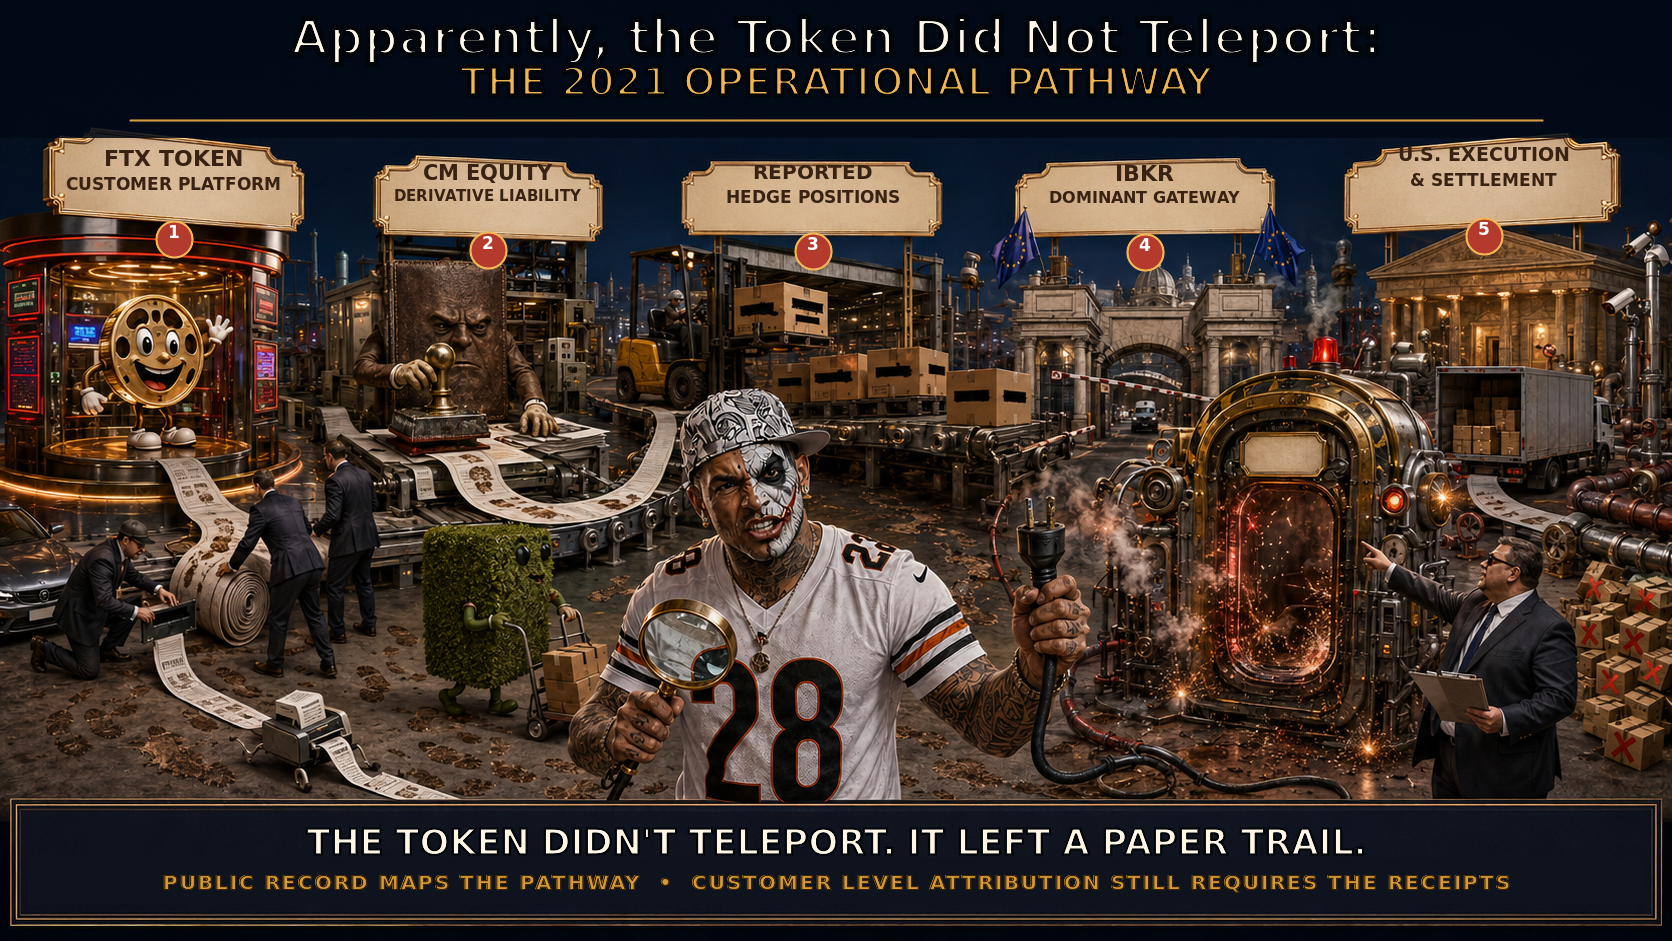
Apparently, the Token Did Not Teleport: The 2021 Operational Pathway
FTX and CM Equity product documents, reported hedge activity, Interactive Brokers routing infrastructure, Citadel's June 2021 AMC covered order footprint and the settlement trail, mapped in one sourced investigation without pretending the missing customer level receipt has already been found.
Finding: The pathway existed and can be tested. A specific CM Equity AMC order executed by Citadel is not established by the public aggregate reports.
The public record maps the pathway. Customer level attribution still requires the receipts.09
EVIDENCE REPORT • JULY 29, 2026
AMC: The Half of June They Told Retail to Stop Studying
The 4.6 million contract June 2 options event, dealer hedging, short interest, FTDs, off exchange routing and the records still hidden from public view. Documented facts, supported inferences and open questions are separated throughout the 30 page report.
A forensic reconstruction of AMC's June 2021 price, settlement, threshold list, short interest and off exchange record, including the unnamed $385 million Apex trade and the participant ledgers still needed to identify the actors.
FTX bankruptcy table AMC/GME labels, claim estimation math and OCC intraday risk records. The report marks what is confirmed, what is not confirmed and which source level records remain missing.
Published findings only. Active investigations remain private until reviewed, sourced and approved for release. No price predictions. No final accusations without evidence.
DISCLAIMER
The AMC Ape Cage provides independent commentary, research, entertainment and satire. Nothing on this site is financial, investment, legal or tax advice. Always review original sources and consult a qualified professional before making decisions.